Knowing a bond’s coupon tells you how much interest it pays. Understanding its market price takes a little more explanation, because that price can change even while the coupon stays fixed. Convexity helps you understand those changes. For investors in bonds and debt mutual funds, it adds useful detail to the picture that duration provides.
Table of Contents
What is convexity?
In bond investing, convexity describes the bend in the price-yield curve. It measures how the size of a bond’s price response changes as its yield moves. Duration gives an initial estimate based on a straight line. Convexity adjusts that estimate for curvature, helping explain price movements more accurately when yields change by larger amounts.
Source: Reserve Bank of India, Government Securities Market in India: A Primer, section 27.4.
Key Takeaways
- Bond convexity captures the curvature that a duration-only price estimate leaves out.
- Positive convexity adds to estimated gains when yields fall and reduces estimated declines when yields rise.
- Negative convexity can occur when early redemption or prepayment features restrict price appreciation.
- Duration and convexity should be used together when estimating a bond’s response to yield changes.
- A useful investment comparison also considers credit quality, liquidity, price and the investor’s time horizon.
Relationship between bond prices and interest rates
For a fixed-rate bond, a higher required market yield generally means a lower price. A lower required yield generally means a higher price. Imagine that investors can now earn more from similar newly issued bonds. To remain competitive, an older bond with smaller fixed payments would usually need to trade at a lower price.
The reverse applies when market yields decline. Investors may be willing to pay more for the older bond’s fixed payments. This price adjustment changes the yield available to a buyer without changing the bond’s coupon.
Bond duration and convexity
Modified duration estimates the percentage price movement associated with a small change in yield. Convexity measures the additional effect created by the curved price-yield relationship.
For instance, an annual modified duration of five gives an approximate 5% price decline for a one-percentage-point rise in yield, before adding the convexity adjustment.
The two measures have distinct roles:
| Measure | What it tells you | How it is used |
| Modified duration | The bond’s initial price sensitivity | Supplies the first-order price-change estimate |
| Convexity | How the price-yield relationship curves | Refines the duration-based estimate |
| Macaulay duration | The weighted average time to receive cash flows | Describes cash-flow timing |
Macaulay duration and modified duration are related, but they are not interchangeable in a price-change calculation.
Source: CFA Institute, 2026 curriculum reading on Yield-Based Bond Duration Measures and Properties.
How convexity works
The effect of convexity depends on the direction of the curve.
Types of bond convexity
Positive and negative convexity produce different adjustments to the initial duration estimate:
| Type | Effect when yields fall | Effect when yields rise | Examples |
| Positive convexity | The estimated price increase is larger | The estimated price decrease is smaller | Option-free fixed-rate government and corporate bonds |
| Negative convexity | The estimated price increase is smaller | The estimated price decrease is larger | Callable bonds in relevant yield ranges and mortgage-backed securities with prepayment features |
These comparisons are against the duration-only estimate, rather than a promise about an investment’s return.
For a callable bond, the issuer can repay the bond early under its terms. When falling yields make that decision more attractive, investors may receive their money sooner, limiting how far the bond’s price can rise. Negative convexity depends on the likelihood of redemption; it does not apply to every callable bond at every yield.
Significance of convexity
For comparable option-free fixed-rate bonds, longer maturities, smaller coupons and lower yields generally produce higher convexity. Cash-flow timing explains much of this relationship. Payments due further in the future contribute more strongly to curvature than payments arriving sooner.
Sources: CFA Institute, 2026 curriculum readings on Yield-Based Bond Convexity and Portfolio Properties, and Valuation and Analysis of Bonds with Embedded Options.
How to calculate convexity
A convexity calculation brings together the bond’s scheduled payments, price and yield to maturity. The payment intervals and yield convention must match.
Bond convexity formula
For an option-free bond valued on a coupon date, with annual payments and an annually compounded yield:
The symbols represent:
- C is annual convexity.
- P is the bond’s full price.
- CFₜ is the cash flow in year t, including principal in the final year.
- y is the annual yield to maturity, expressed as a decimal.
- n is the number of remaining annual periods.
Mathematically, this is the second derivative of the discounted cash-flow price with respect to yield, divided by price. For semi-annual bonds, calculations use half-year periods and the corresponding yield per period. Periodic convexity must then be annualised consistently.
Using convexity with modified duration
The approximate proportional price change is:
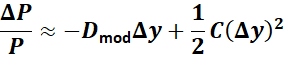
Dₘₒ𝒹 represents modified duration, while Δy represents the change in yield.
A rise from 7% to 8% is a one-percentage-point change, entered as 0.01. The result is multiplied by 100 to express the price movement as a percentage.
For bonds whose expected payments change with interest rates, analysts use effective duration and effective convexity. These measures incorporate different cash-flow outcomes under yield scenarios.
Sources: CFA Institute, 2026 curriculum readings on yield-based convexity and curve-based fixed-income risk measures.
Example of bond convexity
Neha, a 32-year-old schoolteacher, wants to understand how a yield change could affect a bond she is considering.
Take a hypothetical fixed-rate government bond worth ₹10,000. Assume an annual modified duration of seven and annual convexity of 64.
The duration calculation produces a 7% movement for a one-percentage-point yield change. The convexity adjustment adds:
½ × 64 × 0.01² = 0.0032, equivalent to 0.32%.
The estimates become:
| Yield movement | Estimate from duration | Estimate after adding convexity | Estimated bond value |
| One percentage point lower | +7.00% | +7.32% | ₹10,732 |
| One percentage point higher | -7.00% | -6.68% | ₹9,332 |
The figures shown are for illustrative purpose only
Neha can see the adjustment separately: It adds 0.32 percentage points to the estimated gain and reduces the estimated decline by the same amount.
The calculation considers an immediate yield movement. Coupon income, trading costs and changes caused by the passage of time are excluded.
Real-life applications and risk management with bond convexity
Investors and fund managers use convexity to answer practical questions about fixed-income holdings:
- Estimating price changes: Adding convexity helps refine the response calculated from modified duration.
- Comparing investments: Bonds with similar duration may have different convexity, producing different responses to the same yield movement.
- Reviewing debt fund portfolios: Available convexity measures add context to information about duration, maturity and holdings.
- Testing scenarios: Managers can examine different yield movements before adjusting fixed-income portfolios.
One assumption deserves attention: Portfolio calculations often model an equal yield change across maturities. In practice, short-term and long-term yields may move differently, so other measures can be needed to assess those changes.
Does convexity matter for debt mutual fund investors in India?
Yes. A debt mutual fund’s NAV reflects the value of its underlying investments. When yields change, the prices of its bond holdings can change too.
Convexity helps explain part of that response, especially in portfolios containing longer-maturity securities. The result depends on the holdings’ duration, payment structures and embedded options.
It provides context for reading NAV movements alongside credit quality, liquidity and other factors affecting the portfolio.
Source: AMFI, Risks in Mutual Funds, including its explanations of interest rate, credit, liquidity and prepayment risks.
How can investors assess convexity?
For a directly held bond, start with its maturity, coupon, yield and any call or put features. Review duration and convexity figures where they are available.
For debt mutual funds, scheme factsheets and portfolio disclosures help explain the holdings and their maturity profile. Convexity is not necessarily published in every factsheet.
Institutional investors may also compare the convexity of their assets with future payment obligations when planning portfolio exposure.
Common mistakes when reading convexity
Convexity is more useful when the comparison behind it is clear:
- Overlooking duration: A bond can have substantial positive convexity and still respond strongly to yields because its duration is high.
- Equating convexity with total risk: A favourable price adjustment says little about an issuer’s credit quality or how easily the bond can be sold.
- Comparing unlike securities: Different maturities, coupons, yields and embedded options affect the result.
- Expecting an exact forecast: The duration-and-convexity formula approximates price changes; substantial yield movements may require fuller repricing.
- Leaving out investment needs: Your intended holding period and liquidity requirements remain part of the decision.
Options-based convexity strategies
In broader investment discussions, convexity can describe nonlinear exposure created through options. Fixed-income managers may use interest rate options to change a portfolio’s response to market movements.
The expression upside convexity can refer to exposure whose gains increase more rapidly as conditions become favourable.
Options involve costs, including the premium paid by a buyer. A strategy can underperform in steady or quiet markets if the benefit from market movements is insufficient to cover those costs.
What does it mean to roll a bond?
An investor who replaces one bond with another may describe the transaction as rolling the investment. The replacement can alter maturity, yield or portfolio exposure.
Roll-down return refers to a different effect. A bond’s remaining maturity shortens with time. If the yield curve remains upward-sloping and unchanged, the yield associated with that shorter maturity may be lower, contributing to price appreciation.
This movement along the yield curve is separate from convexity’s measurement of price curvature.
FAQs
What is bond convexity?
Bond convexity describes the curvature in a bond’s price-yield relationship. It helps account for the difference between a straight-line duration estimate and the curved response of bond prices.
What is the difference between duration and convexity?
Modified duration measures initial price sensitivity to a yield change. Convexity supplies the adjustment for curvature. Together, they give a more detailed estimate than duration alone.
How do you calculate bond convexity?
For an option-free fixed-rate bond, calculate convexity using its scheduled cash flows, full price and yield to maturity. Use payment periods and compounding conventions that match the bond.
What causes negative convexity?
Features that change repayment timing can create negative convexity. A callable bond, for example, may become more likely to be redeemed as yields decline, restricting further price appreciation.
Is higher bond convexity better?
With duration and other characteristics comparable, greater positive convexity provides a more favourable adjustment to price movements. The price paid, yield, credit quality and liquidity still influence the investment’s suitability.
Which bonds have the highest convexity?
Long maturities, low coupons and low yields generally increase convexity for option-free fixed-rate bonds. At an equal maturity and yield, a zero-coupon bond has higher convexity than a comparable coupon-paying bond.
How does convexity help during market downturns?
Convexity helps assess the part of a bond’s price movement associated with changing yields. Positive convexity moderates estimated declines relative to duration alone, but the outcome also depends on credit spreads and other market changes.
Why does convexity matter if I hold a bond to maturity?
It helps explain the market value available if you need to sell before maturity. For a non-callable bond paying as agreed, interim price changes leave contractual redemption proceeds unchanged. Reinvestment rates on coupons can still affect realised returns.
How does convexity affect debt mutual funds?
Yield changes alter the valuation of a fund’s bond holdings. Convexity influences that price response and therefore contributes to NAV movements, alongside duration and other portfolio factors.
Related Searches