Sovereign Gold Bonds and Gold ETFs provide exposure to gold without requiring investors to store physical metal. Their structures, returns, liquidity and tax treatment, however, differ considerably.
SGBs are government securities linked to gold prices and pay fixed interest on their original issue price. Gold ETFs are mutual fund schemes that seek to track domestic gold prices and trade on stock exchanges.
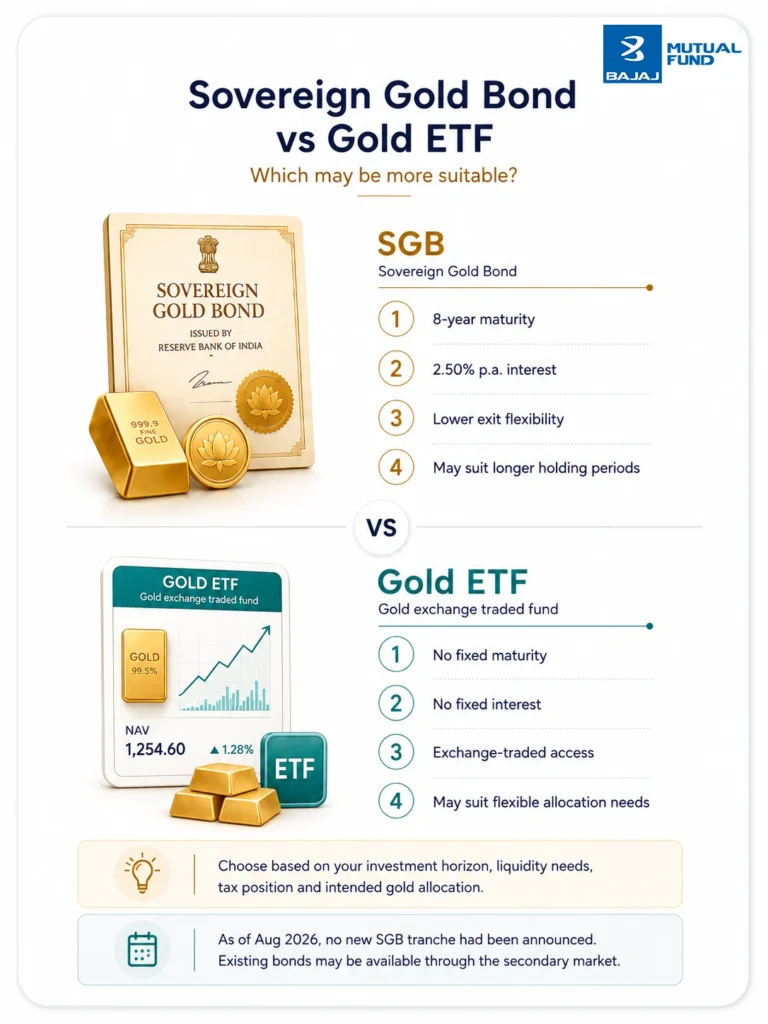
This sovereign gold bond vs gold ETF comparison explains the differences that matter when choosing between them. One current factor is especially relevant: no new SGB tranche had been announced as of August 2026, although existing bonds may be available through the secondary market.
Table of Contents
Sovereign Gold Bond vs Gold ETF at a glance
The principal differences in gold ETF vs gold bond investing are:
| Aspect | Sovereign Gold Bonds | Gold ETFs |
| Structure | Government securities denominated in grams of gold | Mutual fund schemes traded on stock exchanges |
| Issuer | Issued by the RBI on behalf of the Government of India | Offered by asset management companies and regulated by SEBI |
| Gold exposure | Redemption value is linked to the applicable price of gold | NAV seeks to track domestic gold prices |
| Additional income | Interest at 2.50% per annum on the original issue price | No fixed interest |
| Tenure | Eight years | No fixed maturity |
| Availability | New subscriptions only during announced tranches; existing bonds may trade on exchanges | Generally available during exchange trading hours |
| Liquidity | Varies by tranche and secondary-market demand | Varies by the ETF’s trading activity |
| Exit | RBI redemption after the fifth year on specified dates, or exchange sale when held in demat form | Sale through the exchange during trading hours |
| Demat account | Not compulsory for primary subscription; required for exchange trading | Required for exchange transactions |
| Recurring cost | No fund-management fee | Expense ratio applies |
| Other costs | Brokerage and bid-ask spread may apply to exchange transactions | Brokerage, statutory charges and bid-ask spread may apply |
| Main risks | Gold-price risk, liquidity risk and price discount | Gold-price risk, tracking difference and exchange-liquidity risk |
| Taxation | Depends on how the bond was acquired and redeemed | Depends on the holding period and applicable tax law |
Key Takeaways
- SGBs have an eight-year maturity and pay interest at 2.50% per annum on the original issue price, while Gold ETFs do not pay fixed interest.
- Gold ETFs can generally be traded during exchange hours, whereas SGB liquidity depends on the availability of buyers and sellers for a particular tranche.
- From April 1, 2026, the SGB capital-gains exemption applies only to original subscribers who hold their bonds continuously until maturity.
- Gold ETFs involve an expense ratio and tracking difference, while exchange-traded SGBs can carry brokerage, bid-ask spreads and a premium or discount to gold value.
- Suitability depends on availability, investment horizon, liquidity needs, purchase route, tax position and intended gold allocation.
Understanding Sovereign Gold Bonds
Sovereign Gold Bonds, or SGBs, are government securities denominated in grams of gold. The RBI issues them on behalf of the Government of India whenever a new tranche is announced.
The holder does not receive physical gold at maturity. The redemption amount is calculated using the applicable price of gold under the scheme rules.
Previously issued SGBs generally have the following features:
- Minimum primary-market subscription of one gram of gold
- Eight-year maturity
- Interest at 2.50% per annum on the original issue price
- Half-yearly interest payments
- RBI premature redemption after the fifth year on specified interest-payment dates
- Eligibility for stock-exchange trading when held in demat form
- Redemption value linked to the applicable market price of gold
Interest is calculated on the original issue price, not the price subsequently paid on the exchange. An investor purchasing an SGB at a premium or discount should account for this when estimating the effective yield.
Source: RBI Sovereign Gold Bond FAQs.
Are new Sovereign Gold Bonds currently available?
No new SGB tranche had been announced as of August 2026. The most recent primary issue was SGB 2023-24 Series IV, issued in February 2024.
Investors seeking an SGB may therefore need to purchase an existing dematerialised bond through a recognised stock exchange. Availability and liquidity are not assured.
Before purchasing a listed SGB, check:
- The exchange price relative to the prevailing value of gold
- Original issue price used to calculate interest
- Remaining tenure and maturity date
- Trading volume and bid-ask spread
- Upcoming interest-payment dates
- Tax treatment of a secondary-market purchase
A discount to the implied gold value does not automatically make a bond attractive. It may reflect limited liquidity, a long remaining tenure or weaker demand for the tranche.
Source: RBI notification for SGB 2023-24 Series III and IV
Pros and cons of investing in SGBs
SGBs combine gold-price exposure with fixed interest, but their tenure, availability and liquidity require careful consideration:
Advantages of SGBs
The principal advantages relate to interest income, sovereign backing and freedom from physical-gold concerns:
- Their value is linked to movements in the applicable price of gold.
- Interest is paid at 2.50% per annum on the original issue price.
- Physical storage, purity testing and insurance are not required.
- No recurring fund-management fee applies.
- Eligible original subscribers can receive a capital-gains exemption when the applicable conditions are satisfied.
- The payment obligation carries sovereign backing, although the market value remains exposed to gold-price movements.
Limitations of SGBs
Investors should weigh the longer tenure, restricted availability and secondary-market constraints before investing:
- Primary investment is possible only when a new tranche is announced.
- The stated maturity period is eight years.
- RBI premature redemption is available only after the fifth year and on specified dates.
- Some listed tranches may have limited trading activity.
- An exchange sale may take place at a discount to the implied value of gold.
- Interest income is taxable.
- Secondary-market purchases do not qualify for the SGB capital-gains exemption under the rules effective from April 1, 2026.
Understanding Gold ETFs
A Gold Exchange Traded Fund is a mutual fund scheme that seeks to track the domestic price of gold. It primarily invests in physical gold that meets the prescribed quality standards and may hold other permitted assets according to its scheme documents.
Gold ETF units are held electronically and traded on recognised stock exchanges. Their market price may change during the trading session according to the value of the underlying assets, gold-price movements and demand for the units.
The scheme’s NAV generally moves with domestic gold prices after accounting for expenses, cash holdings and tracking difference. The exchange price may trade slightly above or below the latest available NAV.
Pros and cons of investing in Gold ETFs
Gold ETFs offer convenient gold exposure, but their costs and trading characteristics also require consideration:
Advantages of Gold ETFs
The main benefits relate to accessibility, flexibility and electronic ownership:
- Units can generally be bought and sold during exchange trading hours.
- Investors receive exposure to gold prices without holding physical metal.
- There is no fixed maturity or mandatory holding period.
- Holdings are maintained electronically in a demat account.
- Investors can compare expense ratios, tracking differences and trading liquidity across schemes.
- Gold exposure can ordinarily be increased or reduced in relatively small quantities.
Limitations of Gold ETFs
Before investing, consider the expenses, tracking difference and exchange-related limitations:
- A demat account and trading account are required.
- Scheme expenses reduce returns relative to the value of the portfolio.
- Tracking difference can cause performance to vary from domestic gold prices.
- Brokerage and statutory transaction charges may apply.
- Thin trading activity can create an unfavourable bid-ask spread.
- Gold ETFs do not pay fixed interest.
How do SGBs and Gold ETFs compare in returns?
Returns from both products are influenced by domestic gold prices. These prices reflect international gold rates, the rupee-dollar exchange rate, import-related costs and domestic market conditions.
SGB returns can have two components:
- A change in value linked to the applicable price of gold
- Interest at 2.50% per annum on the original issue price
Gold ETF returns primarily reflect domestic gold-price movements after the effect of the expense ratio, cash holdings and tracking difference.
The interest gives SGBs an additional return component, but an exchange buyer’s actual outcome depends on the purchase price. Paying a significant premium can reduce the value of the interest, while purchasing at a discount can improve the effective yield.
Neither product assures gains. If gold prices decline, an SGB’s market value and a Gold ETF’s NAV can also fall.
How do SGBs and Gold ETFs compare in liquidity?
Gold ETFs generally provide greater transaction flexibility because they have no fixed maturity and can ordinarily be traded during exchange hours. Liquidity still differs between schemes, and a thinly traded ETF may have a wider gap between its buying and selling prices. SGBs have two exit routes:
- Eligible RBI premature redemption after the fifth year on specified interest-payment dates
- Sale through a recognised stock exchange when the bond is held in demat form
Describing SGBs as having an absolute five-year lock-in is therefore inaccurate. An exchange sale may be possible earlier, but a buyer or suitable price is not assured.
How do SGBs and Gold ETFs compare in risk?
Both products carry gold-price risk. Their additional risks differ:
Risks associated with SGBs
SGB investors should consider risks beyond the sovereign backing of the payment obligation:
- Gold-price risk: The redemption or market value can decline when gold prices fall.
- Liquidity risk: Some listed tranches may have few active buyers and sellers.
- Price-discount risk: An exchange sale may take place below the value implied by prevailing gold prices.
- Availability risk: Another primary tranche may not be available when an investor wants to invest.
- Opportunity-cost risk: Capital committed for a long period may miss opportunities elsewhere.
Sovereign backing relates to the government’s payment obligation. It does not protect against a fall in gold prices or an unfavourable secondary-market sale.
Risks associated with Gold ETFs
Gold ETFs combine gold-price exposure with scheme-level and exchange-trading risks:
- Gold-price risk: The NAV and exchange price can decline with domestic gold prices.
- Tracking difference: Scheme performance may differ from gold-price movements.
- Liquidity risk: Low trading activity can result in wider bid-ask spreads.
- Market-price deviation: Units may trade above or below NAV.
- Expense impact: Recurring scheme expenses reduce returns.
One product should not be labelled universally safer than the other. Both provide gold exposure, while their liquidity, cost and structural risks differ.
How do SGBs and Gold ETFs compare in costs?
SGBs have no annual fund-management fee. Secondary-market transactions may still involve:
- Brokerage
- Statutory transaction charges
- Bid-ask spread
- A premium or discount to the implied gold value
Gold ETF costs may include:
- Scheme expense ratio
- Brokerage and statutory charges
- Bid-ask spread
- Tracking difference
An ETF’s expense ratio should not be reviewed alone. A low expense ratio may be offset by a larger tracking difference or weak exchange liquidity.
Taxation of Sovereign Gold Bonds and Gold ETFs
Taxation can materially affect a gold ETF vs sovereign gold bond decision.
Taxation of Sovereign Gold Bonds
Interest received from an SGB is taxable according to the investor’s applicable income-tax provisions.
From April 1, 2026, the capital-gains exemption is available only when:
- The investor subscribed to the SGB at its original issue
- The original subscriber held the bond continuously
- Redemption takes place on maturity
An SGB purchased through the secondary market does not qualify for this exemption. An original subscriber who exits before maturity also does not satisfy the conditions.
Capital gains from an exchange sale are taxable according to the applicable holding-period and tax provisions.
Source: Government of India, Explanatory Memorandum to the Finance Bill, 2026.
Taxation of Gold ETFs
Under the tax framework applicable at the time of publication, listed Gold ETF units held for more than 12 months are generally treated as long-term capital assets. Long-term capital gains are generally taxable at 12.5% without indexation. Gains on units held for 12 months or less are generally taxed at the investor’s applicable slab rate.
The tax treatment may vary according to the acquisition date, investor category and future changes in law.
The tax information in this article is based on prevailing laws at the time of publishing the article and is subject to change. Please consult a tax professional or refer to the latest regulations for up-to-date information.
Sovereign Gold Bonds or Gold ETFs: Which may be more suitable?
Neither option is inherently more suitable for every investor. SGBs may suit an investor who:
- Already holds an originally subscribed SGB or has identified a suitably priced listed tranche
- Can remain invested for the required period
- Does not require frequent access to the investment
- Values the additional fixed interest
- Has assessed the bond’s liquidity and tax treatment
Gold ETFs may suit an investor who:
- Prioritises easier entry and exit
- Wants gold exposure when no new SGB tranche is available
- Prefers an investment without a fixed maturity
- Plans to adjust the gold allocation periodically
- Is comfortable with scheme expenses and tracking difference
The choice should also account for the investor’s existing exposure to gold. A disproportionate allocation can make the portfolio overly dependent on the price of a single asset.
Factors to check before choosing
Before making a gold ETF vs gold bond decision, review:
Investment horizon
SGBs have an eight-year maturity, while Gold ETFs have no fixed tenure. The product should match the period for which the money can remain invested.
Liquidity requirement
Gold ETFs usually provide greater flexibility, although execution depends on market liquidity. SGB liquidity can be limited for less actively traded tranches.
Purchase price
For an exchange-traded SGB, compare the quoted price with the prevailing gold value, original issue price, remaining interest payments and maturity date. For a Gold ETF, compare the market price with the latest available NAV.
Tax position
SGB taxation now depends heavily on whether the investor subscribed at the original issue and held the bond continuously until maturity. Gold ETF taxation depends on the holding period and applicable law.
Costs and tracking
Review the ETF’s expense ratio, tracking difference and trading spread. For an SGB, consider brokerage, liquidity and any premium or discount at purchase.
Portfolio allocation
The investment should suit the investor’s goals, risk appetite and existing allocation across gold and other asset classes.
Conclusion
The gold ETF vs SGB comparison is primarily a choice between tenure, liquidity, interest income, availability and taxation.
SGBs provide additional fixed interest and can offer favourable tax treatment to eligible original subscribers who hold the bonds continuously until maturity. New tranches are not currently available, however, and listed SGBs can have uneven liquidity.
Gold ETFs provide easier ongoing access and have no fixed maturity. Their returns are affected by expenses and tracking difference, and they do not pay fixed interest.
The suitable route depends on the investor’s holding period, need for liquidity, purchase route, tax circumstances and intended gold allocation.
FAQs
What is the minimum investment in Sovereign Gold Bonds?
The minimum subscription for a new SGB issue has historically been one gram of gold. No new tranche was open at the time of publication, while exchange purchases depend on the available quantity and quoted price.
Are new Sovereign Gold Bonds available in 2026?
No new SGB tranche had been announced as of August 2026. The most recent primary issue was SGB 2023-24 Series IV in February 2024, although existing dematerialised bonds may be traded on stock exchanges.
Can I buy SGBs from the secondary market?
Yes. Existing dematerialised SGBs can be purchased through recognised stock exchanges. Check the maturity date, original issue price, trading liquidity, quoted premium or discount and applicable tax treatment before investing.
Can Sovereign Gold Bonds be sold before eight years?
Dematerialised SGBs can be sold on a stock exchange, subject to liquidity. RBI premature redemption is separately available after the fifth year on specified interest-payment dates.
Is there a five-year lock-in for Sovereign Gold Bonds?
The five-year condition applies to premature redemption through the RBI. A dematerialised SGB may be sold earlier on an exchange, but execution at a suitable price is not assured.
Do I need a demat account for Gold ETFs?
Yes. A demat account and trading account are generally required to buy and sell gold ETF units on a stock exchange.
Do I need a demat account for Sovereign Gold Bonds?
A demat account is not compulsory for a primary SGB subscription because the bond may be held in certificate form. It is required for buying or selling SGBs through a stock exchange.
Is interest on Sovereign Gold Bonds taxable?
Yes. SGB interest is taxable according to the investor’s applicable income-tax provisions. It is calculated at 2.50% per annum on the bond’s original issue price.
Are secondary-market SGBs tax-free at maturity?
No, under the rules effective from April 1, 2026. The exemption is restricted to original subscribers who hold their SGBs continuously until redemption at maturity.
Which is more suitable for a shorter holding period, SGB or Gold ETF?
A Gold ETF may be more practical for a shorter holding period because it has no fixed maturity and can generally be traded during exchange hours. Gold-price volatility, trading liquidity and costs must still be considered.
Why can an SGB trade below the prevailing value of gold?
An SGB may trade at a discount because of limited liquidity, remaining tenure, tax treatment, market demand or differences between buyers’ and sellers’ price expectations.
What is the main disadvantage of Gold ETFs?
A Gold ETF’s performance can lag domestic gold-price movements because of its expense ratio, cash holdings and tracking difference. Brokerage and an unfavourable bid-ask spread may also affect returns.
Do Gold ETFs pay interest like Sovereign Gold Bonds?
No. Gold ETFs do not pay fixed interest. Their performance primarily reflects domestic gold-price movements after scheme expenses and tracking difference.
Is a Sovereign Gold Bond safer than a Gold ETF?
SGBs carry sovereign backing for the issuer’s payment obligation, while Gold ETFs are regulated mutual fund schemes holding permitted gold assets. Both remain exposed to gold-price movements and have different liquidity and market risks.
Can SGBs and Gold ETFs both be held in a portfolio?
Yes. An investor may retain an existing SGB for long-term exposure while using a Gold ETF for greater transaction flexibility. The combined gold allocation should remain consistent with the investor’s goals and risk appetite.