If you’re 25 and earning ₹30,000 a month, you can start investing for long-term growth without setting aside a large sum. Begin with an amount that fits your budget while you build savings for unexpected expenses.
The next step is deciding where your money should go. An SIP in a mutual fund is one option, but you may also want to consider bank deposits, PPF or NPS for different goals. Let’s work through a monthly budget and see how you could put together a starting plan.
Table of Contents
How much of a ₹30,000 salary should you invest?
Start with the expenses you already have. Once rent, groceries, travel, bills and other commitments are covered, how much can you set aside each month without finding yourself short later?
For some people earning ₹30,000, an SIP of ₹3,000 to ₹6,000 may fit comfortably. If you pay rent or support your family, ₹1,000 or ₹2,000 may be a better starting point. You can increase the amount when your budget has more room.
Here is one possible way to divide a ₹30,000 monthly income:
| Monthly use | Illustrative amount |
| Essentials, such as rent, groceries, bills and travel | ₹17,000 |
| Everyday spending and leisure | ₹5,000 |
| Emergency savings | ₹3,000 |
| Health cover or other protection needs | ₹1,000 |
| Long-term SIP | ₹4,000 |
| Total | ₹30,000 |
The figures shown are for illustrative purpose only
Your own split may look different. Living with family could mean lower rent, while an EMI could take up more of your income. Treat this as a way to organise your money, then change the amounts to suit your life.
What should you take care of as you start?
You can begin investing while gradually building the rest of your financial plan. It helps to make room for three things in your budget.
Keep some money available for emergencies
An emergency fund lets you meet an unexpected expense without drawing on an investment meant for a long-term goal. A common starting target is three to six months of essential expenses. If your essentials cost ₹17,000 a month, that comes to around ₹51,000 to ₹1,02,000.
There is no need to save that amount all at once. In the budget above, ₹3,000 goes towards emergency savings each month while ₹4,000 goes towards a long-term investment. Keep at least some emergency money readily accessible, such as in a savings account, and build the fund gradually.
Check your insurance needs
Health cover can help you manage medical expenses while you continue saving for other goals. If someone depends on your income, you can also consider term life insurance. The amount of cover you need depends on your responsibilities, not just your age.
Account for loan repayments
If you have credit card dues or a high-interest loan, include the repayments before deciding how much to invest. You may still be able to begin with a modest amount and increase it once those payments reduce.
What investment options can you consider at 25?
Think about when you will need the money before choosing where to put it. Money for an emergency needs to be easy to reach. Money for a purchase in a couple of years has a different job from money you are setting aside for retirement.
Here are the main avenues you may consider:
| Option | What it can help you do | What to keep in mind |
| Savings account | Keeping money available for everyday needs and emergencies. | Easy access is the main consideration for this part of your money. |
| Fixed deposit or recurring deposit | Saving through a bank for a goal with a clearer time frame. A recurring deposit lets you contribute regularly. | Check the deposit period, interest rate and terms for withdrawing early. |
| Equity mutual funds and index funds | Investing towards a goal many years away. An SIP lets you contribute a chosen amount regularly. | The scheme’s investment approach and riskometer should suit your goal and comfort with market movements. |
| Debt and hybrid mutual funds | Exploring other mutual fund categories based on the goal. Debt funds invest mainly in debt securities, while hybrid funds combine asset classes. | Categories differ in what they hold and how their value may change, so check the specific scheme. |
| Public Provident Fund (PPF) | Building long-term savings through a government-backed scheme. | PPF has an initial 15-year term and rules for withdrawals, so it is not a place for money you may need soon. |
| National Pension System (NPS) | Investing specifically for retirement through a market-linked pension system. | Understand the investment choices and withdrawal rules, particularly for an NPS Tier I account. |
| Exchange-traded funds (ETFs) | Investing in a fund traded on a stock exchange, often one that tracks an index. | ETFs are held in a demat account; check what the fund tracks and its costs. |
| Direct shares | Owning shares of companies you choose yourself. | You need time to research individual companies and follow your holdings. |
If your employer contributes to an Employees’ Provident Fund (EPF) account for you, remember to include that in your retirement savings picture too.
You do not need to start with every option in this table. On a ₹30,000 salary, a few choices with clear purposes are easier to manage than small amounts spread across many products.
Returns on fixed deposits/savings accounts are fixed, however, returns on mutual funds are subject to market risks.
What could your starting plan look like?
Go back to the sample budget. You are setting aside ₹3,000 a month for emergencies and have ₹4,000 for another goal. What you do with that ₹4,000 depends on when you expect to use it.
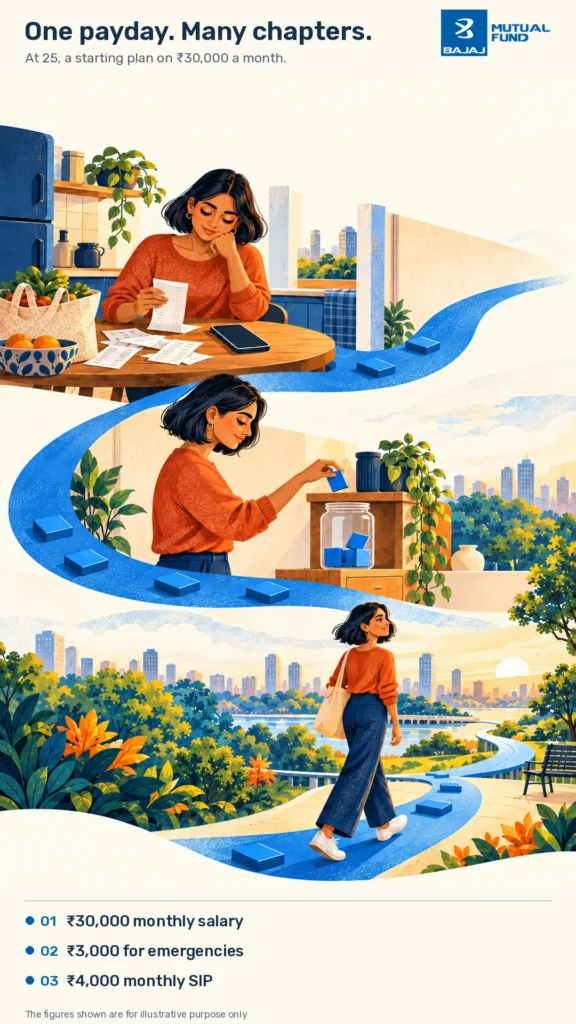
If the goal is many years away, you could explore investing the ₹4,000 through an SIP in one suitable, diversified mutual fund. If you expect to use the money in the next few years, a bank deposit or another option suited to that shorter period may fit better. If you are saving specifically for retirement, you could also look at PPF or NPS after understanding when you can withdraw the money.
Start with the goal that matters to you now. You can add another investment when you have another clear reason for it.
How do you choose a mutual fund for long-term growth?
An SIP is a way to invest regularly in a mutual fund, rather than a separate investment product. The scheme you choose determines where your money is invested.
An index fund aims to track an index. An actively managed diversified equity fund invests according to its stated strategy. A hybrid fund combines asset classes. You do not have to choose several funds when you start with a small monthly amount.
Look at the scheme’s investment objective, what it holds, its costs and its riskometer. Consider how each of those fits your goal and the time you have to reach it. Being 25 may give you years to invest, but your age alone does not decide which fund is right for you.
Why does starting at 25 help?
When returns remain invested, they have the opportunity to contribute to further growth. This is compounding. Its effect may be hard to notice in the early years while you are still building up your investment. Over a longer period, your contributions and any returns have more time to work together.
You do not need to stretch your first salary to make an early start. An amount you can continue investing gives you a base to build on as your income grows.
What could a ₹4,000 monthly SIP grow to?
Suppose you invest the ₹4,000 from the sample budget through an SIP for 10 years. At an assumed annual return of 10%, with each contribution made at the beginning of the month, the illustration works out as follows:
| SIP illustration | Amount |
| Monthly SIP | ₹4,000 |
| Investment period | 10 years |
| Total invested | ₹4,80,000 |
| Estimated value at the end of 10 years | ₹8,26,208 |
| Estimated gain | ₹3,46,208 |
The figures shown are for illustrative purpose only
The calculator is an aid, not a prediction tool. It may provide only an indicative picture.
If ₹4,000 does not fit your budget, enter a smaller amount in the Bajaj AMC SIP calculator. You can change the amount, investment period and assumed return to see how the illustration changes.
How do you start your first SIP?
If you decide that a mutual fund suits one of your goals, you can begin with these steps:
- Choose a monthly amount: Set an SIP amount that leaves room for essentials, other commitments and emergency savings.
- Decide what the SIP is for: Use your goal and the time you have to reach it to shortlist a suitable fund category.
- Compare suitable schemes: Check their investment objectives, holdings, costs and riskometers before choosing.
- Complete KYC: AMFI explains that KYC is required even for a small mutual fund SIP, so complete it or check that your existing details are up to date.
- Set a convenient SIP date: Choose a date shortly after your salary arrives so the monthly debit is easier to plan for.
Can you increase your SIP later?
Yes. You might begin with ₹3,000 a month and move to ₹4,000 after a salary increase, if your budget allows. A step-up SIP lets you plan increases to your monthly contribution. You can try different amounts and time periods in the Bajaj AMC step-up SIP calculator. You can also review and increase an existing SIP yourself when your budget has more room.
FAQs
Is ₹30,000 a month enough to start investing?
Yes. You can start investing on a ₹30,000 monthly income if you have money left after your essential expenses and commitments. The amount could be ₹1,000, ₹3,000 or more, depending on your budget.
How much should I invest each month if I earn ₹30,000?
There is no fixed amount. Some people may be comfortable putting ₹3,000 to ₹6,000 towards long-term investments. If that would leave you short for regular expenses, start with a smaller amount and review it later.
Should I invest only through an SIP?
No. An SIP is a way to invest regularly in a mutual fund. Your wider plan may also include emergency savings, bank deposits, PPF or retirement savings through EPF or NPS, depending on your goals.
Should I choose PPF or an equity mutual fund?
They serve different purposes. PPF is a long-term government-backed savings scheme with withdrawal rules. An equity mutual fund offers market-linked exposure that you can explore for a long-term goal. You could consider either or both based on what you want each investment to do.
Can I start an SIP with ₹500 or ₹1,000?
Yes, some mutual fund schemes allow SIPs of ₹500 or ₹1,000. Check the minimum SIP amount for the scheme you select.
Should I finish building an emergency fund before I invest?
You can build emergency savings and start a small investment alongside each other if your budget allows. Keep money available for immediate needs and add to it gradually.
How do I choose my first mutual fund at 25?
Start with what you are investing for and when you will need the money. For a goal many years away, you could explore a diversified equity mutual fund or index fund if you are comfortable with market movements. Compare schemes by their investment objectives, holdings, costs and riskometers before choosing.
How long should I stay invested for long-term growth?
Let your goal guide the period. Money for retirement can follow a different investment plan from money you expect to use in the next few years. Revisit your plan as the goal gets closer or your circumstances change.