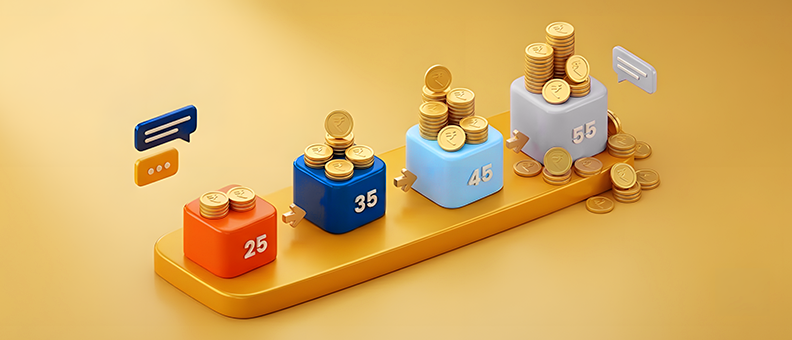
Your investment portfolio will naturally change as life moves forward. At 25, you may be earning and investing for the first time. By 35, family expenses or loan repayments may claim a larger share of your income. At 45, retirement and other major goals may be getting closer. At 55, regular income and easy access to money may need more attention.
A comparison of SIP investment at age 30 vs 45 brings out one important difference: time. Starting at 30 gives each instalment longer to remain invested. Starting at 45 may call for a larger SIP, more time to reach the goal or a different target. The right approach also depends on your income, existing savings, responsibilities and comfort with market movements.
Table of Contents
At 25: Start Small, Stay Consistent
Scenario: You have just started working, have fewer responsibilities, and can invest for long-term goals.
At this stage, time may work in your favour. You can consider starting an SIP in mutual funds and increasing the amount gradually as your income rises. Since long-term goals are far away, some exposure to equity-oriented investments may be considered, based on your risk comfort. Equity investments can fluctuate, so they should be approached with patience.
Key Takeaways
- Your portfolio may need to change as your goals, income and responsibilities evolve.
- Starting an SIP earlier gives each instalment more time, but beginning later can still help you work towards a planned goal.
- At 25, an emergency fund and regular investments can provide a useful starting point.
- At 35 and 45, linking investments to specific goals and reviewing the portfolio regularly becomes more relevant.
- At 55, liquidity, medical expenses and retirement-income needs may have a greater influence on asset allocation.
You can also begin building an emergency fund. A mix of savings account balance, fixed deposits, or liquid funds may help you manage unexpected expenses.
Possible focus at 25
- Starting an SIP
- Building an emergency fund
- Buying suitable health insurance
- Keeping spending under control
- Learning basic money management
At 35: Balance Growth and Responsibilities
Scenario: You may have a home loan, family expenses, child-related goals, or higher monthly commitments.
By 35, your income may be higher, but your responsibilities may also increase. Your portfolio can have a mix of equity-oriented investments for long-term goals and options that may offer relatively more stability, such as fixed deposits, recurring deposits, or debt-oriented funds for short-term needs.
If you have goals like buying a house, planning for a child’s education, or building retirement savings, you may want to separate each goal clearly. This can help reduce the likelihood of using long-term investments for near-term expenses.
Possible focus at 35:
- Goal-based SIPs
- Emergency fund
- Term insurance and health insurance
- Loan repayment planning
- Separate investments for separate goals
Read more: I’m 25 And Earning ₹30k A Month How Should I Start Investing For Long-Term Growth
At 45: Review and Rebalance
Scenario: You may be earning more, but retirement and major family goals may now feel closer.
At this age, it may be useful to review your portfolio more carefully. If your portfolio has moved too heavily towards one asset class, you may consider rebalancing it. This means bringing your investments closer to a suitable mix based on your goals and risk comfort.
You may still need potential growth for long-term goals, but you may also want to reduce the likelihood of taking more risk than required. Debt-oriented options, fixed deposits, and other relatively stable choices may have a larger role for goals that are less than five years away.
Possible focus at 45:
- Reviewing asset allocation
- Rebalancing the portfolio
- Planning for retirement
- Reducing costly loans
- Creating goal-wise investment buckets
At 55: Focus on stability and income needs
Retirement may be approaching, and the savings built over the years may soon need to support regular expenses.
An investment portfolio for a 55-year-old in India may need two separate buckets: money required over the next few years and money meant for later in retirement. The first bucket may include relatively stable and accessible options such as fixed deposits, suitable debt funds or eligible government-backed savings schemes.
The asset allocation for a 55-year-old need not remove growtScenarioh-oriented investments altogether. Retirement may last for several years, so a part of the portfolio could remain invested for longer-term needs. The mix should reflect expected withdrawals, regular sources of income, medical costs and comfort with market movements.
Possible focus at 55
- Planning a dependable flow of retirement income
- Keeping near-term expenses in accessible options
- Setting aside money for medical emergencies
- Reviewing how much capital needs greater stability
- Planning withdrawals across different investments
SIP investment at age 30 vs 45: What really changes?
Your age matters less than your goals, the time available and the financial commitments competing for your money:
| Planning factor | Starting an SIP at age 30 | Starting an SIP at age 45 |
| Common goals | Buying a home, building long-term wealth or planning for retirement | Retirement, children’s education or other goals that may be closer |
| Time available | A longer investment period provides more time to build the required amount | A shorter period may require a higher SIP amount or a review of the goal |
| SIP amount | A smaller amount started early can be increased as income grows | The amount should reflect the target, existing savings and years remaining |
| Investment approach | Longer-term goals may allow greater exposure to equity, depending on risk appetite | Each goal may need a different mix of equity, debt and other assets |
| Existing savings | The portfolio may still be at an early stage | Existing investments should be considered before adding new SIPs |
| Financial commitments | Responsibilities may be fewer, though this differs for every investor | Home loans, education costs and family expenses may influence the amount available |
| Emergency planning | Building an emergency fund alongside investing can create a useful foundation | Emergency savings become especially relevant when several major goals are approaching |
| Portfolio reviews | Periodic reviews can keep investments aligned with changing goals | More frequent reviews may help as the time available for important goals becomes shorter |
Conclusion
Your portfolio at 25, 35, 45, and 55 may look different because your financial life changes with time. The focus may move from starting early, to balancing responsibilities, to reviewing risk, and finally to planning for retirement income. A suitable approach is to review your investments regularly and align them with your current needs, future goals, and risk comfort.
FAQ
How is SIP investment different at age 30 vs 45?
SIP investment at age 30 vs 45 mainly comes down to how much time you have and the goals you’re investing for. At 30, you may have a longer investment horizon, giving your money more time to grow through compounding. At 45, goals like retirement or a child’s education may be closer, so balancing growth and stability can become more important. While starting earlier may offer more time for growth, starting an SIP at 45 can still be a useful way to work towards your financial goals.
What should my investment portfolio look like at different ages?
Your portfolio may change with age. At 25, the focus may be on SIPs and long-term growth. At 35, balancing investments with family goals and loans may become important. At 45, reviewing and rebalancing your portfolio can help. At 55, stability, liquidity, and retirement planning may take priority.
How should I invest at age 25, 30, 35, 45, and 55?
Your investment approach may evolve as your goals and responsibilities change. At 25, focus on starting SIPs, building an emergency fund, and developing good financial habits. At 30, you may consider increasing your investments as your income grows while continuing to work towards long-term goals. At 35, balance investments with family and financial commitments. At 45, review and rebalance your portfolio as major goals and retirement planning become more important. At 55, prioritise capital preservation, liquidity, and retirement income planning.
How much equity should I have in my portfolio by age?
There is no fixed equity allocation for every age. The right mix depends on your goals, time horizon, and risk comfort. Younger investors may consider higher equity exposure, while those nearing retirement may prefer a larger allocation to relatively stable investments.
What may an ideal mutual fund portfolio for a 35-year-old focus on?
An ideal mutual fund portfolio for a 35-year-old cannot be defined by age alone. It may include equity-oriented investments for distant goals and relatively stable options for money required sooner. The mix should reflect family responsibilities, loans, emergency savings, investment horizon and risk comfort.
How should I invest at age 25, 30, 35, 45 and 55?
At 25 and 30, consider building an emergency fund and starting regular long-term investments. At 35, organise investments around specific goals. At 45, review the portfolio and reduce unnecessary risk for nearby goals. At 55, plan for liquidity and retirement withdrawals.