
If you earn profits from your mutual fund investments in a financial year, you typically need to report those gains when filing your Income Tax Return (ITR). The way these investments are disclosed depends on the type of mutual fund, the nature of the income, and how long these investments were held.
Understanding how to show mutual fund investment in ITR starts with identifying what needs reporting: capital gains or losses, IDCW income and eligible deductions. This article explains the filing process and the records you need.
Table of Contents
What are the types of income from mutual funds?
Before we learn about ITR, it helps to understand the different types of income/gains generated from mutual funds and rules that govern its disclosure. Here are the broad types of income from mutual fund:
IDCW income
This is the income that can be released by mutual funds to investors who have opted for the Income Distribution cum Capital Withdrawal (IDCW) plan. This was earlier called the dividend plan, and for taxation purposes, these are taxed as dividends.
Capital gains
Capital gains are profits earned when mutual fund units are sold or redeemed for more than their acquisition cost. There are two types:
- Short-term capital gains (STCG): Gains on equity-oriented mutual fund units held for 12 months or less.
- Long-term capital gains (LTCG): Gains on equity-oriented mutual fund units held for more than 12 months.
Other mutual fund categories follow different holding-period rules. Gains on specified mutual fund units acquired on or after 1 April 2023 are treated as short-term regardless of the holding period.
Read Also: How to claim tax benefits on mutual funds (ELSS)?
Do mutual fund investments need to be reported in the ITR?
Mutual fund investments generally need to be reported in the ITR when they generate income or a capital gain or loss. Merely purchasing or continuing to hold mutual fund units does not usually create taxable income.
The purchase of securities and units of mutual funds may appear in your Annual Information Statement (AIS), but a purchase does not itself create taxable income. Separate disclosures may apply when claiming an ELSS deduction or completing applicable asset schedules.
Here are the transactions that may require reporting:
- Redeeming or selling units and realising a capital gain or loss.
- Switching between schemes or plans, since a switch is treated as a redemption followed by a fresh purchase.
- Receiving an Income Distribution cum Capital Withdrawal (IDCW) payout.
Source: Income Tax Department, Annual Information Statement guidance.
Tax on mutual fund income and gains
How mutual fund taxed depends on many factors, including the type of income. Here’s a breakdown:
Taxation of IDCW payouts
Before 2020, IDCW income from mutual funds was tax-free as fund houses paid Dividend Distribution Tax (DDT). However, after 2020, DDT was removed, and the income is now taxed at the hands of investors based on their income tax slab. It is filed under ‘Income from Other Sources’.
Additionally, fund houses deduct a 10% TDS (Tax Deducted at Source) under Section 194K of the Income Tax Act, 1961, if the total payout to an investor exceeds ₹10,000 in a financial year. Investors can also claim the deducted TDS while filing their income tax return and only pay the remaining tax liability.
Taxation of capital gains provided by mutual funds
Capital gains taxation depends on the fund’s classification, acquisition date and holding period. For FY 2025–26, the treatment is as follows:
1. Equity funds and equity-oriented funds
- STCG on units held for 12 months or less is taxed at 20%.
- LTCG on units held for more than 12 months is taxed at 12.5% on aggregate qualifying gains exceeding ₹1.25 lakh in the financial year, without indexation.
- The ₹1.25 lakh threshold is shared across qualifying gains from equity-oriented funds, listed equity shares and business trust units.
2. Debt funds and debt-oriented hybrid funds
Gains on specified mutual fund units acquired on or after 1 April 2023 are treated as short-term capital gains regardless of holding period and taxed at the applicable slab rate. Units acquired before that date follow the applicable holding-period rules.
For AY 2026–27, specified mutual funds include funds investing more than 65% of their proceeds in debt and money market instruments, and qualifying funds investing in such funds, measured using the prescribed method.
3. Hybrid funds
- Funds qualifying as equity-oriented funds receive equity taxation. This generally requires at least 65% investment in listed equity shares of domestic companies, measured using the prescribed method.
- Funds qualifying as specified mutual funds receive the treatment described above for units acquired on or after 1 April 2023.
- Other hybrid funds follow the applicable holding-period rules. Having less than 65% equity exposure does not automatically make a fund subject to debt-fund taxation.
Applicable surcharge and cess are additional.
Source: Income Tax Department, capital-gains guidance and Section 50AA of the Income-tax Act, 1961.
How to file ITR for mutual funds: Step-by-step process
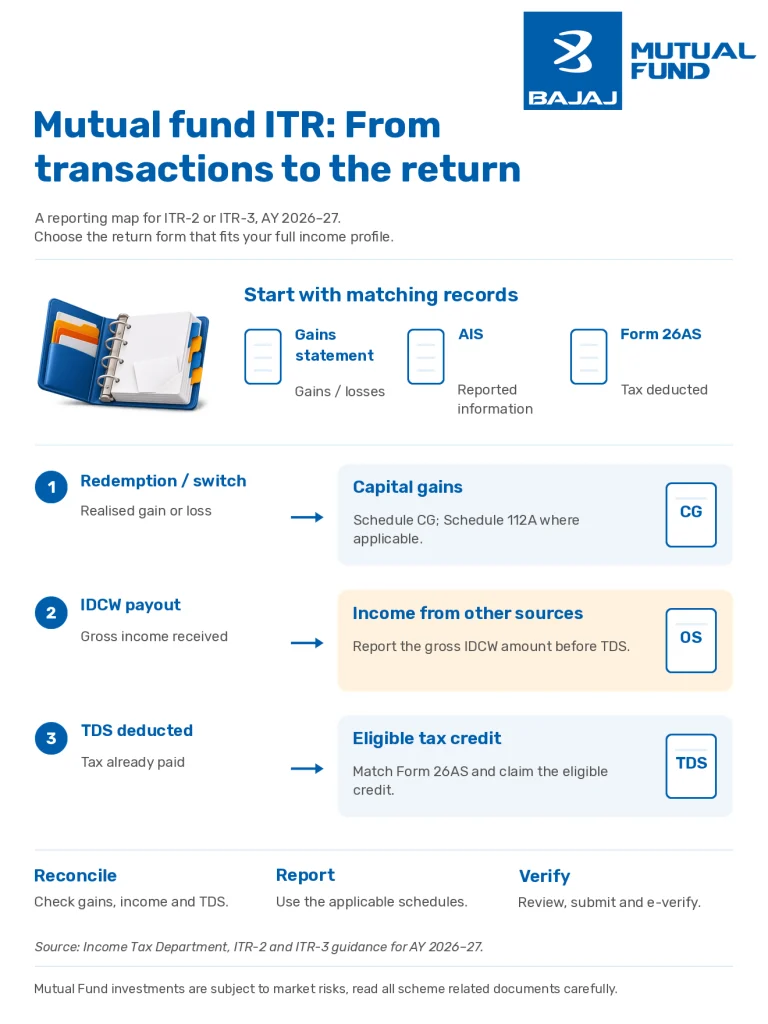
Here is a broad overview of filing your ITR for mutual fund investments.
Step 1: Gather relevant records
Keep your Consolidated Account Statement, capital gains statement, AIS, TIS, Form 26AS and bank statements handy. Use them to check your transactions, realised gains or losses, IDCW income and TDS details.
Step 2: Select applicable ITR form
Choose the form based on all your sources of income:
- ITR-1 is used by eligible resident individuals with total income up to ₹50 lakh and long-term capital gains under Section 112A of up to ₹1.25 lakh.
- ITR-2 applies if you have capital gains but no business or professional income.
- ITR-3 may apply if you also have business or professional income.
Step 3: Log in to tax filing portal
Log in to the income tax department’s e-filing portal, select AY 2026–27 for income earned during FY 2025–26, and choose the applicable form. Check all pre-filled details against your own records before proceeding.
Step 4: Report capital gains
Enter the short-term and long-term capital gains or losses in Schedule CG. Eligible long-term gains from equity-oriented mutual funds should additionally be reported in Schedule 112A.
Step 5: Report IDCW income and TDS
Report IDCW income under Income from Other Sources. If TDS has been deducted, verify it against Form 26AS and claim the eligible credit in the return.
Step 6: Pay any remaining tax
Review the tax calculated after accounting for your income, gains, losses, TDS and advance tax. If an amount is still payable, pay it as self-assessment tax and check that the payment is reflected in the return.
Step 7: Review and submit
Review the details, submit the return and complete the verification process. You can e-verify using Aadhaar OTP, net banking, an Electronic Verification Code or another available method.
The return must generally be verified within 30 days of filing. Otherwise, it may be treated as invalid.
How to calculate and report capital gains and losses
Now that we’ve seen the general process of filing returns, let’s look at the specific details of how to calculate and report capital gains or losses in the ITR form.
Identify the relevant transactions
Use your capital gains statement and Consolidated Account Statement to identify all redemptions, sales and switches made during the financial year. Check the purchase date, transaction date, number of units, cost of acquisition and redemption value for each transaction.
Classify the gains or losses
Classify each transaction as a short-term or long-term capital gain or loss. This depends on factors such as:
- Type of mutual fund
- When the units were purchased
- How long they were held
- Date on which they were sold, redeemed or switched
Calculate the capital gain or loss
Calculate the capital gain or loss by subtracting the cost of acquisition and eligible transfer expenses from the sale or redemption value. A positive amount is a gain; a negative amount is a loss. Check the calculation against your capital gains statement.
Report the details in the applicable schedules
Enter the short-term and long-term capital gains or losses under the relevant sections of Schedule CG. Eligible LTCG from equity-oriented mutual fund units must also be entered in Schedule 112A.
Set off eligible capital losses
Capital losses can be adjusted against capital gains, subject to the following rules:
- A short-term capital loss can be set off against short-term or long-term capital gains.
- A long-term capital loss can be set off only against long-term capital gains.
Capital losses cannot generally be adjusted against salary, interest, IDCW income or other non-capital-gains income.
Carry forward unadjusted losses
If the full capital loss cannot be adjusted during the same year, the remaining amount may be carried forward for up to eight assessment years. However, to do so, the ITR for the year in which it arose must be filed within the prescribed due date.
How to show mutual fund IDCW income in ITR
Dividend income from mutual funds, now called IDCW income from mutual fund investments, is categorized under the head “Income from Other Sources” in your ITR form. You will need to declare the gross dividend amount received.
Mutual fund houses are mandated to deduct Tax Deducted at Source (TDS) at 10%, if it exceeds ₹10,000. This TDS amount will be reflected in your Form 26AS and you can claim credit for this TDS while filing your ITR, which helps reduce your final tax liability.
Always reconcile your dividend income details with your Consolidated Account Statement (CAS), Form 26AS, and Annual Information Statement (AIS) to ensure accuracy before filing your ITR.
Which ITR to file for income and gains from mutual funds?
The ITR form you need depends on the type of income and capital gains you have during the year:
- ITR-1: This form applies if you are a resident individual with total income up to ₹50 lakh and either have no capital gains or only long-term gains of up to ₹1.25 lakh from equity-oriented mutual funds or listed shares. You cannot use it if you have short-term capital gains or capital losses.
- ITR-2: Used if you have short-term gains from any mutual fund category, gains from debt-oriented mutual funds, long-term equity gains above ₹1.25 lakh, or capital losses, and you do not have business or professional income.
- ITR-3: Applies if you also have business or professional income.
Read Also: How to Claim Tax Benefits on Mutual Fund Investments?
How to save tax on mutual funds
The main mutual fund option that offers tax benefits is an Equity Linked Savings Scheme (ELSS). ELSS is an equity mutual fund category that qualifies for a deduction under Section 80C of the Income-tax Act, 1961, under the old tax regime.
Under this section, investments of up to Rs. 1.5 lakh in a financial year made in one or more applicable avenues can be deducted from an individual’s taxable income. The avenues listed under Section 80C of the Income Tax Act, 1961, include but are not limited to:
- ELSS mutual funds
- Public Provident Fund
- Sukanya Samriddhi Yojana
- Tax saving fixed deposits
This makes ELSS mutual funds suitable for those seeking tax benefits as well as long-term growth potential through equity investments. However, they have a lock-in period of three years (which is the shortest among all Section 80C of the Income Tax Act, 1961 options).
Other ways in which investors can reduce their tax outgo include:
- Using the equity LTCG exemption: Long-term capital gains from eligible equity-oriented mutual funds share an annual ₹1.25 lakh exemption with other qualifying gains under Section 112A. Holding eligible units for more than 12 months and planning redemptions across financial years may help you use this exemption. Consider your investment goals, cash needs and exit loads before redeeming.
- Setting off capital losses: Short-term capital losses can be adjusted against short-term or long-term capital gains. Long-term capital losses can be adjusted only against long-term capital gains.
- Panning redemptions: Spreading eligible equity fund redemptions across financial years may help you make use of the annual LTCG exemption. However, tax should not be the only factor. Your goals, cash needs and exit loads also matter.
Read Also: What are tax-saving mutual funds?
Documents required for filing ITR
- Annual consolidated statement: Obtained from mutual fund houses or registrar and transfer agents. Shows all transactions and redemptions.
- Capital gains statement: Highlights taxable capital gains (STCG and LTCG).
- Form 26AS: Reflects TDS, if applicable.
- Bank account statements: Helps verify IDCW payouts and transactions.
- PAN and Aadhaar Card: Mandatory for filing.
Common mistakes to avoid while filing ITR for mutual funds
Here are some mistakes investors may make when filing their tax returns:
- Not reporting all capital gains – When disclosing gains, investors may forget to consider profits from redemptions. Even small, short-term or long-term gains need to be reported.
- Ignoring IDCW income – Investors may overlook the fact that IDCW payouts they receive from mutual funds are taxable and must be included under ‘income from other sources’.
- Mismatched PAN/Aadhaar details – Errors in essential information can lead to potential delays and rejection.
- Not differentiating between short-term and long-term capital gains – Equity and debt mutual funds have different holding periods and tax rates. Reporting them incorrectly can potentially attract notices.
- Skipping losses – Some investors forget to report capital losses in their ITR. Reporting is important because these losses can either be offset against capital gains in the same year (tax-loss harvesting) or, if unutilized, carried forward for to adjust against future gains.
- Overlooking TDS for NRIs – If you are non-resident investor it is important that you declare the TDS deducted on your mutual fund scheme.
Conclusion
Filing ITR for mutual fund investments may initially appear complicated, but a structured approach simplifies the process. Maintain accurate records, disclose all types of income, and consult a tax expert if needed. Proper filing ensures compliance with tax regulations and helps you leverage mutual fund tax benefits effectively.
Filing your Income Tax Returns (ITR) for mutual fund investments can appear complex due to various tax implications. However, with a clear understanding of the rules and careful record-keeping, the process can be streamlined. By staying informed about the latest tax provisions and utilizing available resources, you can fulfill your tax obligations effectively and ensure compliance. If in doubt, consulting a tax advisor can be a suitable approach to ensure precise and efficient ITR filing for your mutual fund holdings. This blog answers common questions like ‘where to show mutual fund investment in ITR 1’, ‘how to show mutual fund investment in income tax return’ and ‘where to show mutual fund income in ITR-2’.
FAQ
Which ITR should be filed for capital gains on mutual funds in ITR?
Choose ITR-1 if your only capital gains are LTCG of up to ₹1.25 lakh from equity-oriented mutual funds and total income is up to ₹50 lakh. If you have any other mutual fund gains or losses, use ITR-2. If you have any business or professional income, Use ITR-3.
Under which section of the Income Tax Act is mutual funds income in ITR taxed?
For FY 2025–26, qualifying equity-oriented fund gains fall under Section 111A for short-term gains and Section 112A for long-term gains. Other funds follow the applicable capital-gains provisions, including Section 50AA where relevant. IDCW income is generally reported under “Income from Other Sources”.
Is TDS deducted from mutual fund returns?
For resident investors, TDS is generally not deducted from mutual fund capital gains. IDCW payouts generally attract 10% TDS when aggregate payouts by the payer exceed ₹10,000 during the financial year, subject to applicable exceptions. Separate TDS rules apply to non-residents.
Where to show mutual fund investment in ITR-1?
Report IDCW income under “Income from Other Sources”. For AY 2026–27, eligible individuals can also report Section 112A long-term capital gains up to ₹1.25 lakh in the designated capital-gains section. Eligible ELSS investments can be claimed under Section 80C in the old regime. Other ITR-1 eligibility conditions must also be met.
What are the consequences of not showing mutual fund income in ITR?
Failing to disclose mutual fund income can result in penalties, interest on unpaid taxes, and scrutiny by tax authorities, potentially leading to legal consequences. This includes declaring sale of securities and units of mutual fund in ITR.
What is TDS (Tax Deducted at Source) on mutual fund dividends?
Yes, if your total tax credits and payments exceed your final tax liability. Report the gross IDCW income, claim the eligible TDS credit shown in Form 26AS and file your return to claim the refund.
How do I show the sale of securities and units of mutual funds in ITR?
Report the sale of securities and units of mutual funds in ITR through the applicable capital-gains schedules. In ITR-2 or ITR-3, use Schedule CG and, where applicable, Schedule 112A. Eligible ITR-1 filers should use its designated LTCG section.
How are SIP purchases treated in ITR?
Each SIP instalment is a separate purchase with its own acquisition date and holding period. A purchase of mutual fund units in ITR is not reported as taxable income merely because you invested. Eligible ELSS instalments can qualify for Section 80C deductions under the old regime.
Related Searches